Buying on Sullivan’s Island calls for more than finding a beautiful coastal home: it takes a clear financing plan, careful property review, and a closing timeline built around island-specific details. This guide maps the journey from preapproval through final signatures so you can make decisions with fewer surprises and more confidence.
Begin With a Financing Plan That Fits the Property
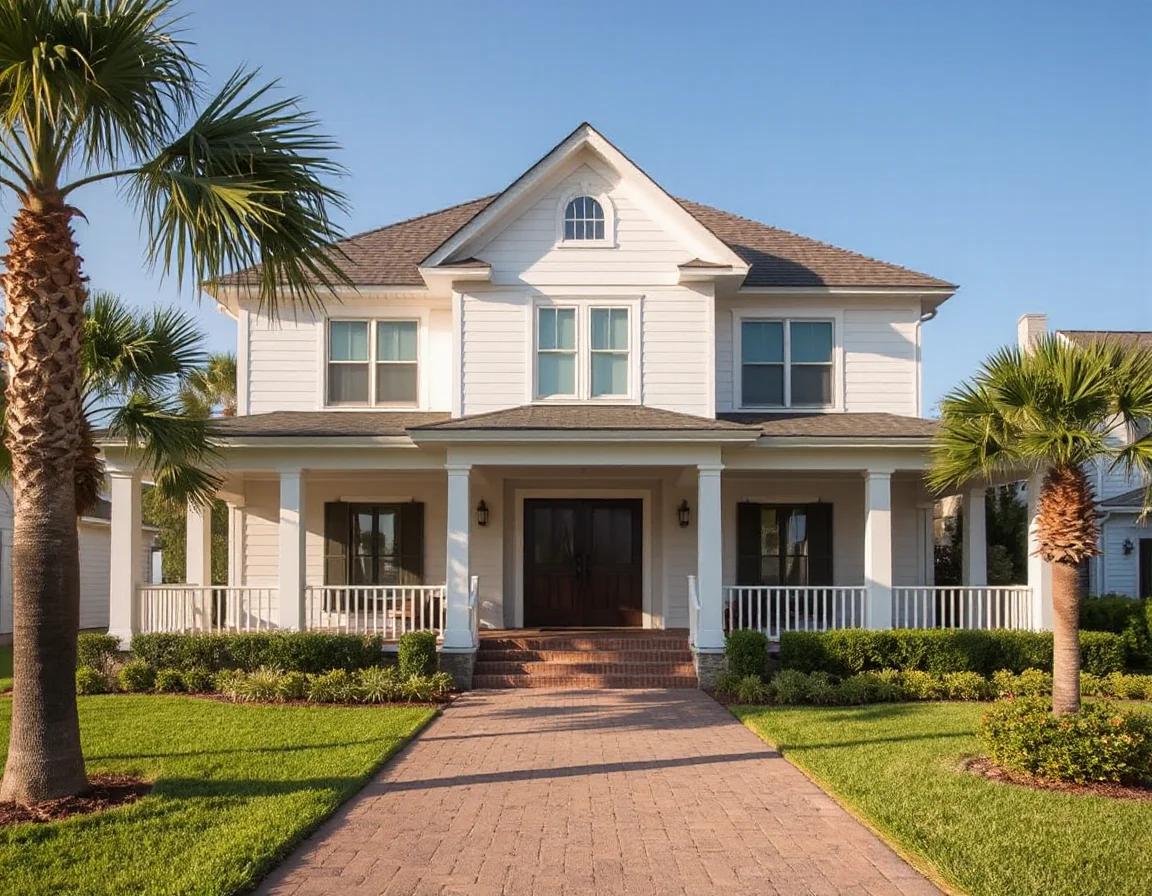
Sullivan’s Island home buying often starts well before the first showing. Inventory can be limited, and properties may range from renovated historic cottages to newer elevated residences with water views, porches, pools, and substantial outdoor spaces. A current mortgage preapproval gives you a practical price range, clarifies the cash needed for a down payment and closing costs, and helps position an offer when the right property becomes available.
Ask your lender to explain more than the maximum loan amount. Discuss the monthly payment at several purchase prices, including estimated property taxes, homeowner’s insurance, flood insurance where applicable, association dues if any, and ongoing maintenance reserves. Coastal ownership can involve expenses that are not always apparent in an online listing, so a complete monthly and annual budget is more useful than a single headline number.
For buyers using financing, it is also wise to learn the lender’s documentation timeline at the outset. Income, assets, credit, insurance quotes, appraisal requirements, and property-condition questions can all affect underwriting. Keeping accounts stable, avoiding major new credit purchases, and responding promptly to document requests can help maintain momentum once you are under contract.
On a coastal purchase, request preliminary insurance and flood-zone information early in the search—not after an offer is accepted. Those figures can materially change the total cost of ownership.
Cash buyers benefit from preparation too. Proof of funds should be current, readily verifiable, and aligned with the anticipated purchase price and closing expenses. Whether financing or paying cash, the goal is the same: enter negotiations with a well-supported plan and enough flexibility to address inspection findings, insurance requirements, or a competitive offer situation.
Search With the Island’s Physical and Regulatory Details in Mind
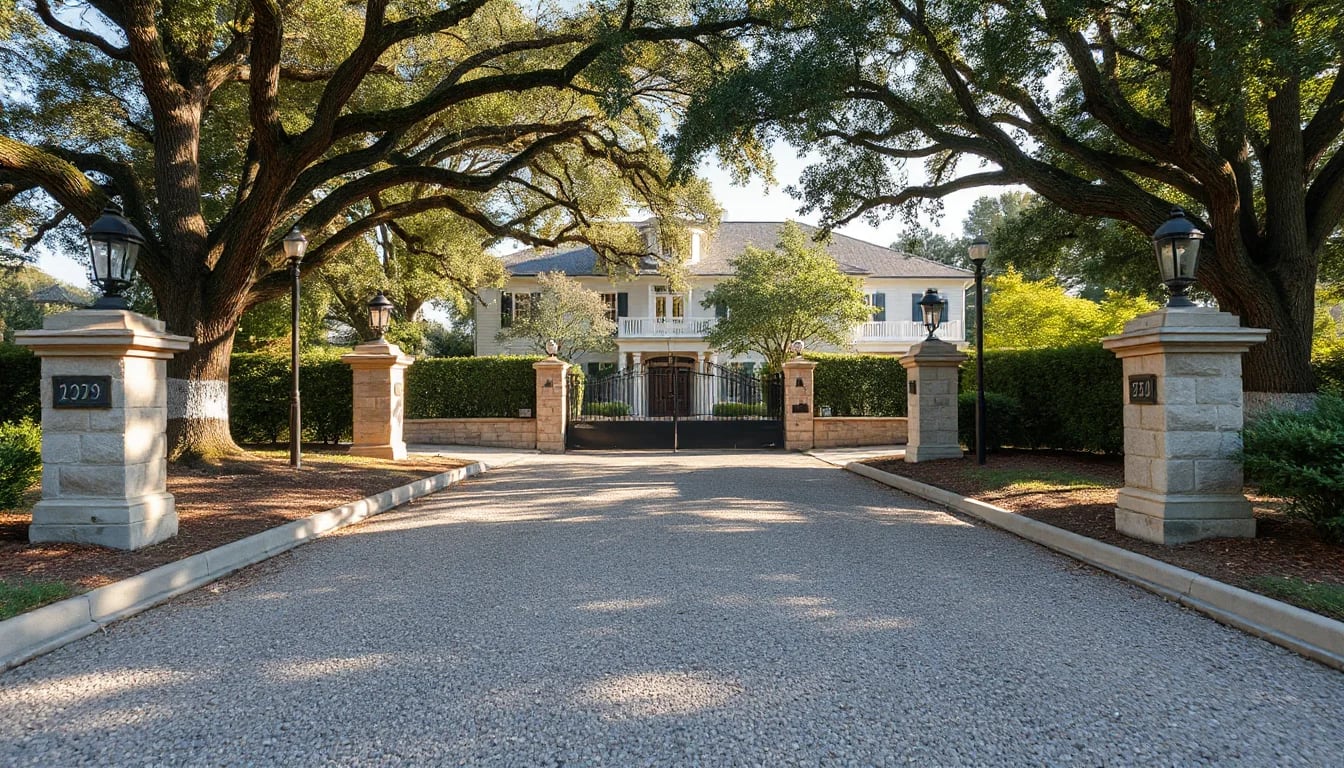
The appeal of Sullivan’s Island is tied to its coastal setting, beach access, maritime landscape, and distinctive residential architecture. That setting also makes due diligence especially important. Instead of evaluating only bedrooms, finishes, and lot size, consider how an individual property functions in its specific location: elevation, drainage, access, parking, outdoor improvements, views, and proximity to water can all shape ownership decisions.
A thoughtful showing checklist can keep the search focused. Note the home’s foundation or elevation type, visible exterior materials, roof age where disclosed, window and door condition, deck or porch maintenance, and any features such as pools, docks, bulkheads, generators, or landscaping systems. Ask for available permits, survey information, utility details, and records for major improvements. These items do not replace professional inspections, but they help you compare properties consistently.
Historic character is another important consideration. Some homes may be subject to local review processes, and exterior changes, demolitions, additions, or renovations can require approvals and permits. Before planning a major project, verify the applicable rules directly with the appropriate local offices and review the property’s existing approvals. A purchase decision should account for both the home as it stands today and the realistic path for any future changes.
It is equally helpful to distinguish between a water view, waterfront location, beach access, and water access. Each description can mean something different in practical terms. Survey lines, easements, public rights-of-way, tidal conditions, and ownership of improvements should be reviewed with the relevant professionals before closing. Clear questions during the search phase can prevent assumptions from becoming costly surprises later.
Search Sullivan's Island listings
Build a Team for the Due-Diligence Period
Once an offer is accepted, the contract timeline becomes the framework for action. Your real estate professional can help coordinate dates and communications, while inspectors, lenders, insurance professionals, attorneys, surveyors, and specialized contractors address their respective parts of the transaction. White-glove service is most valuable when it turns a long list of moving pieces into an organized, understandable process.
General home inspections are an important starting point, but a coastal property may warrant additional evaluations depending on age, condition, and features. Buyers may consider inspections or opinions relating to roofing, HVAC systems, plumbing, electrical systems, moisture intrusion, wood-destroying organisms, pools, docks, seawalls, drainage, or structural components. The right scope depends on the property; an inspector or qualified specialist can advise what further review is appropriate.
Read each report carefully and separate immediate health, safety, structural, or functional concerns from routine maintenance and cosmetic preferences. A well-maintained older home may still show wear, while a recently renovated home may have systems that deserve review. The purpose of due diligence is not to expect a perfect report. It is to understand the condition of the home, determine which items matter most to you, and make informed choices within the contract deadlines.
Move From Contract to Closing With Fewer Last-Minute Surprises
During the weeks leading to closing, several workstreams may advance at once. The lender orders or reviews the appraisal if financing is involved, the closing attorney completes title work, insurance coverage is finalized, and the buyer reviews repair agreements or seller-provided documents. Stay attentive to dates for the due-diligence period, loan commitment, appraisal, title review, final walkthrough, and required funds transfer.
For coastal homes, insurance should be treated as a central closing item rather than a final checkbox. Coverage availability, deductibles, wind provisions, and flood requirements can vary by property and carrier. Obtain written quotes and confirm the policy effective date with enough lead time for your lender and closing team. If the home has a pool, dock, detached structure, or other specialized feature, ask how that feature is addressed in the coverage conversation.
The final walkthrough is for confirming the property’s agreed-upon condition, included items, and completed repairs—not for reopening the entire inspection process. Bring the contract, repair documentation, and a practical checklist.
The final walkthrough typically occurs shortly before closing. Check that agreed repairs appear complete, included fixtures and personal property remain in place, systems are operating as reasonably expected, and no new damage is visible. If questions arise, raise them promptly through the proper channels so the closing team can evaluate the issue and discuss available options.
At closing, you will review and sign transaction documents, confirm funds, and receive the information needed for ownership and possession according to the contract. Keep a dedicated file with your settlement statement, title documents, inspection reports, warranties, insurance policies, surveys, contractor records, and major system information. This organized record can be useful for maintenance planning, future improvements, insurance renewals, and eventual resale.
Make the Purchase a Long-Term Ownership Plan
A Sullivan’s Island home is best approached as both a place to enjoy and a property to maintain thoughtfully. After closing, create a seasonal maintenance schedule for exterior surfaces, drainage, roofing, HVAC servicing, landscaping, porches, and any water-adjacent improvements. Document work as it is completed, and use qualified local professionals when specialized coastal experience is needed.
Strong preparation does not remove every variable from a real estate transaction, but it gives you a reliable way to respond when questions arise. With a meaningful preapproval, property-specific due diligence, early insurance planning, and a disciplined closing checklist, buyers can move from the first showing to the closing table with a more complete understanding of both the opportunity and the responsibility of island ownership.