Sullivan’s Island vacation-rental decisions are rarely just about nightly rates. Local rules, permitting timelines, flood exposure, insurance, seasonality, maintenance, and the property’s location all shape the return an owner may actually keep. A disciplined comparison turns a beautiful coastal property from a tempting idea into a well-defined ownership plan.
Start With the Rules Before Estimating Revenue
Sullivan’s Island has a limited land area, distinctive coastal character, and a regulatory environment that deserves careful review before a buyer treats short-term rental income as part of a purchase decision. A listing’s past rental history can be useful context, but it is not a promise that a future owner can operate the property in the same way. Rules, permit availability, zoning interpretations, and local administrative requirements can change, so the first question is not “What can this home earn?” but “What use is currently permitted for this specific property?”
Begin with the Town of Sullivan’s Island and confirm the current requirements directly with the appropriate municipal offices or qualified local counsel. Ask whether the address is eligible for the rental use being considered, whether a license or permit is required, whether there are registration and renewal obligations, and whether there are limits related to rental duration, occupancy, parking, signage, noise, or on-site contacts. If a property is governed by a homeowners association or condominium regime, review its documents separately; private restrictions may be more restrictive than municipal rules.
It is also important to distinguish between a traditional long-term lease, a furnished seasonal arrangement, and a short-term accommodation. These categories can carry different rules, tax treatment, management needs, and income patterns. An owner evaluating a second home may decide that periodic personal use plus longer furnished stays is the better fit; another may prioritize a property that supports a more active rental calendar. The right approach depends on the property’s verified eligibility and the owner’s goals, not on a generic island-wide estimate.
A permit, license, or prior rental record should be verified for the exact address before rental income is included in an offer strategy or financing conversation.
Build an ROI Model That Uses Net Income, Not Headlines
Gross rental revenue is the most visible number in a vacation-rental projection, but it is only the starting point. A realistic return-on-investment model begins with projected booked nights and an achievable average daily rate, then subtracts the full cost of operating and owning the property. This approach makes it easier to compare two homes with very different price points, layouts, locations, and maintenance profiles.
For revenue, use several scenarios rather than a single optimistic forecast. A conservative case might assume slower booking pace, lower shoulder-season demand, and additional owner-use dates. A moderate case can reflect a balanced annual calendar. A stronger case may assume favorable booking performance, but it should still account for weather disruptions, reservation cancellations, repairs, and periods when the home is unavailable for service work. Coastal rental demand can be seasonal, and an annual total can look solid while monthly cash flow varies widely.
- Acquisition costs: purchase price, lender fees, inspections, appraisal, legal review, and closing costs.
- Recurring ownership costs: property taxes, insurance, utilities, internet, landscaping, pest service, and association assessments where applicable.
- Rental operations: management fees, booking-platform fees, cleaning, linens, consumables, guest communication, and local compliance costs.
- Capital reserves: exterior upkeep, HVAC replacement, roofing, appliances, furnishings, decks, windows, and storm-related repairs.
- Taxes and professional guidance: lodging-related taxes, income-tax planning, accounting, and legal review tailored to the ownership structure.
A simple formula is helpful: projected gross revenue minus operating expenses, debt service if applicable, taxes, and annual reserves equals estimated cash flow. From there, buyers can compare cash-on-cash return, debt-service coverage, and total return assumptions. The exact calculation will vary by financing and tax situation, but the discipline of including every recurring cost is universal.
Search Sullivan’s Island listings
Coastal Ownership Costs Can Change the Comparison
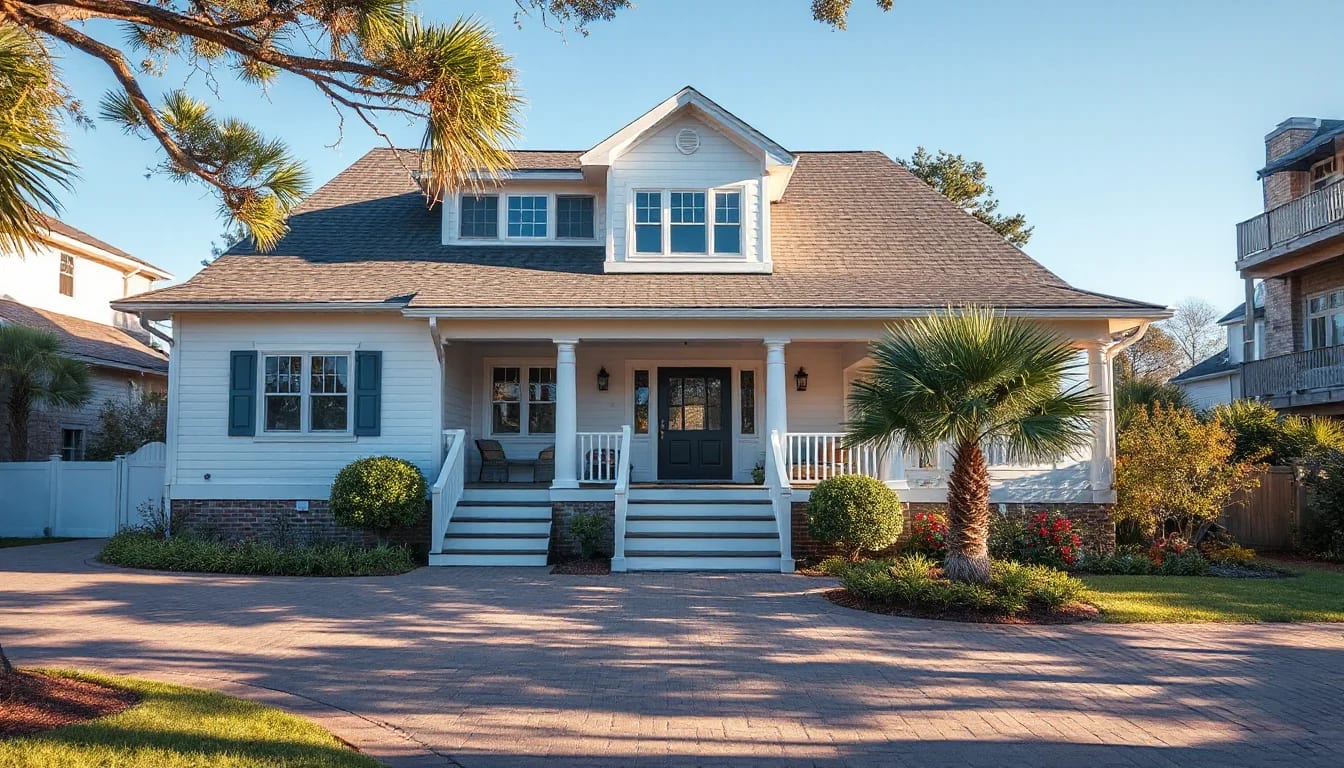
Two homes with similar bedroom counts and similar projected rental rates can produce markedly different ownership costs. On Sullivan’s Island, flood-zone designation, elevation, construction type, age, roof condition, wind coverage, drainage, proximity to salt air, and the condition of decks and exterior systems can all affect annual expenses. A home that appears less expensive at purchase may require greater reserves, while a newer or extensively updated property may offer a more predictable near-term maintenance profile.
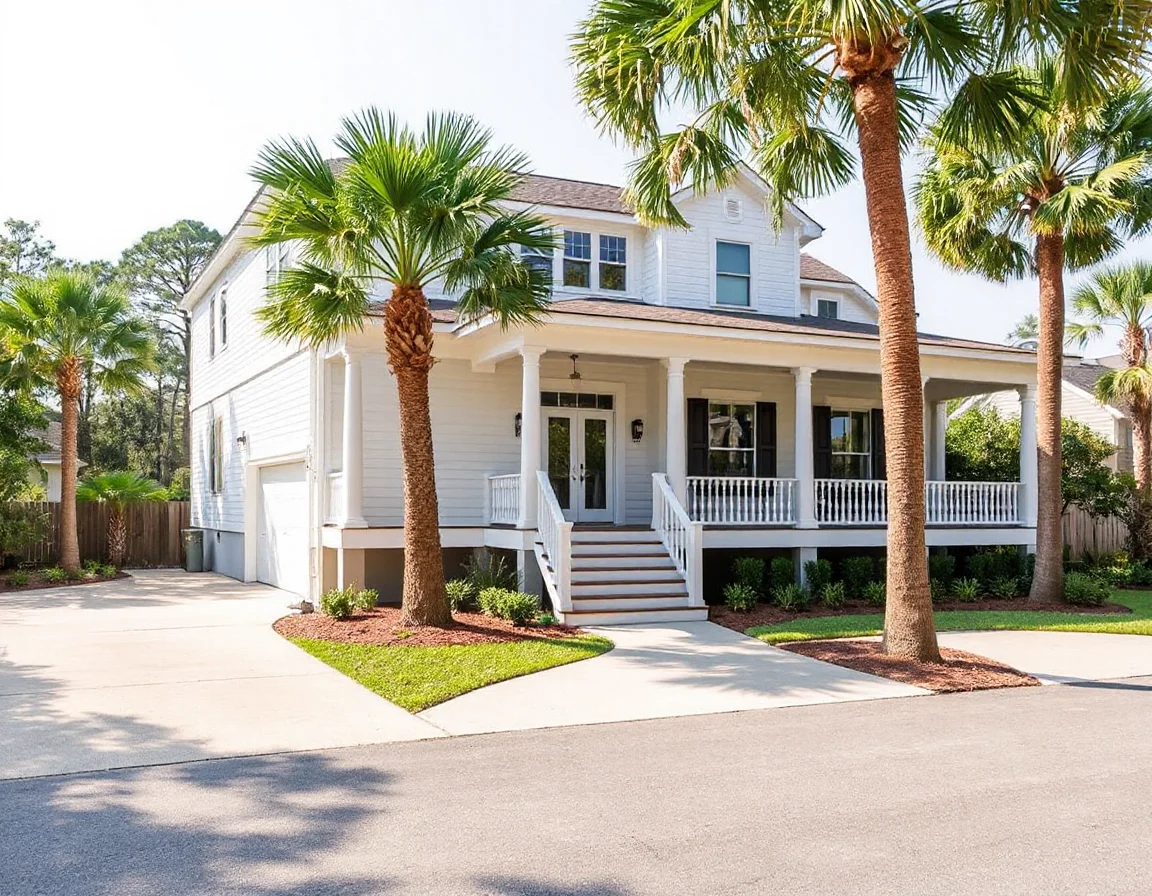
Insurance deserves special attention. Obtain property-specific quotes early rather than relying on a rough percentage of the purchase price. Coverage needs can include homeowners, wind and hail, flood, liability, and possibly umbrella coverage. Deductibles and exclusions matter as much as premiums, especially when evaluating the financial impact of a severe weather event. Buyers should also ask whether a lender has additional insurance requirements and whether the insurer’s underwriting assumptions match the intended occupancy and rental use.
Maintenance is another major variable. Salt air and coastal humidity can accelerate wear on exterior paint, hardware, HVAC components, windows, railings, outdoor furnishings, and mechanical systems. A thorough inspection should look beyond cosmetic condition. Roof age, foundation and elevation details, crawlspace or enclosure conditions, drainage, exterior fasteners, decks, stairs, and windows are all practical items to understand before setting an annual reserve.
For furnished rentals, inventory replacement is part of the operating plan. Bedding, towels, kitchen equipment, outdoor furniture, electronics, and décor all have useful lives. Properties that photograph well and function smoothly tend to need a consistent refresh budget. That cost is not a flaw in the model; it is the price of maintaining a property that remains appealing, practical, and ready for each arrival.
Location Features Influence Both Demand and Expenses
On an island market, location is more nuanced than distance to the beach. Buyers may compare walkability to public beach access points, views, lot orientation, traffic patterns, parking configuration, access to the commercial district, and proximity to public recreation. These details can influence a visitor’s experience, but they also influence property operations. Parking constraints, outdoor shower placement, storage for beach equipment, stair access, landscaping, and waste collection logistics can affect management efficiency.
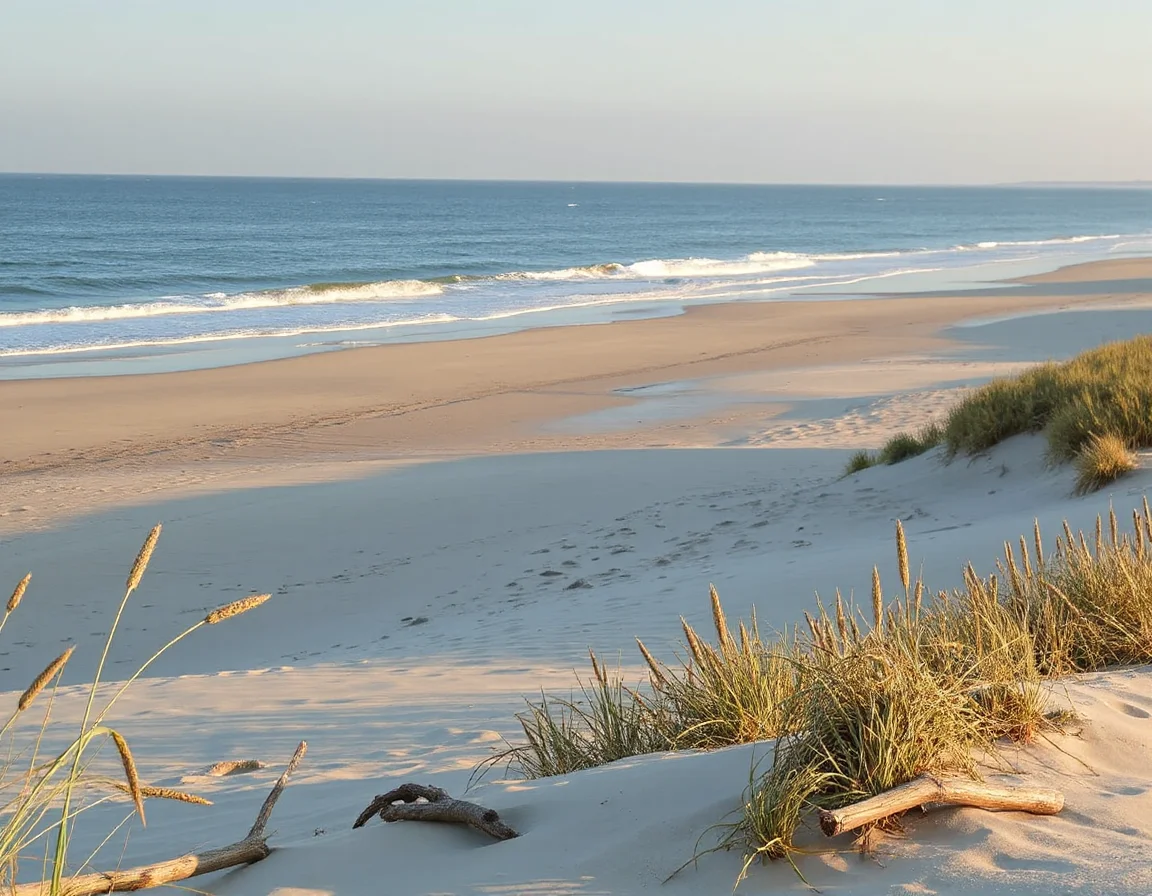
Waterfront, marsh-facing, and ocean-adjacent properties may offer distinctive settings, yet they can also bring additional exposure to wind, salt, erosion concerns, dock or bulkhead maintenance, and specialized insurance questions. A comparison should pair each lifestyle feature with its corresponding ownership obligation. The goal is not to avoid coastal property; it is to understand its full operating profile before choosing a purchase price and rental strategy.
A property’s layout can matter as much as its address. Useful storage, durable finishes, flexible sleeping arrangements, outdoor living areas, and clear arrival flow can support rental operations. At the same time, elaborate landscaping, pools, elevators, docks, or extensive outdoor features should be evaluated for service requirements and reserve needs. A feature that supports stronger rates may still reduce net income if operating costs rise faster than revenue.
The strongest comparison is often the property with the clearest verified use, manageable operating profile, and a reserve budget that still works in a conservative booking scenario.
Compare Management Options and Personal-Use Priorities
Management is a major ROI decision, not merely an administrative choice. Full-service local management may handle reservations, pricing, cleaning coordination, inspections, emergency response, maintenance oversight, tax collection, and guest communication. That support comes with a fee, which should be modeled carefully. Self-management may reduce commissions, but it requires time, reliable vendors, compliance awareness, and a dependable system for responding to issues.
Ask each prospective manager for a clear explanation of services, fee structure, owner statements, pricing strategy, maintenance authorization limits, linen programs, marketing channels, and cancellation handling. Request examples of how they prepare homes for storms, address after-hours maintenance, and document property condition between stays. Comparing managers on net owner proceeds rather than commission percentage alone can reveal meaningful differences.
Personal use should also be written into the financial model. Blocking peak dates for owner stays can reduce gross income, but those dates may be central to the reason for owning the property. There is no universally correct balance. The best plan is one that honestly values both the financial objective and the owner’s intended enjoyment of the home.
Make the Decision With Current, Property-Level Information
A Sullivan’s Island vacation-rental analysis works best when it is specific, current, and conservative. Verify the rules for the address, confirm all permit and association requirements, obtain insurance and management estimates, inspect the home thoroughly, and model several booking scenarios. Then compare each option on projected net income, cash flow resilience, maintenance exposure, and how well it fits the desired ownership experience.
Charleston Realty and Jayson Wingfield can help buyers evaluate available Sullivan’s Island properties through the lens of location, condition, waterfront considerations, and long-term ownership goals. With careful due diligence, buyers can move beyond eye-catching revenue projections and make a decision grounded in the details that matter after closing.