Buying a first home on Sullivan’s Island means balancing a remarkable coastal setting with a careful financial and property-condition review. From lending preparation and insurance estimates to elevation, flood zones, and local regulations, the strongest offers are built on clear information—not guesswork. This guide lays out a practical path from early budgeting to closing day.
Start With the Real Cost of a Coastal Purchase
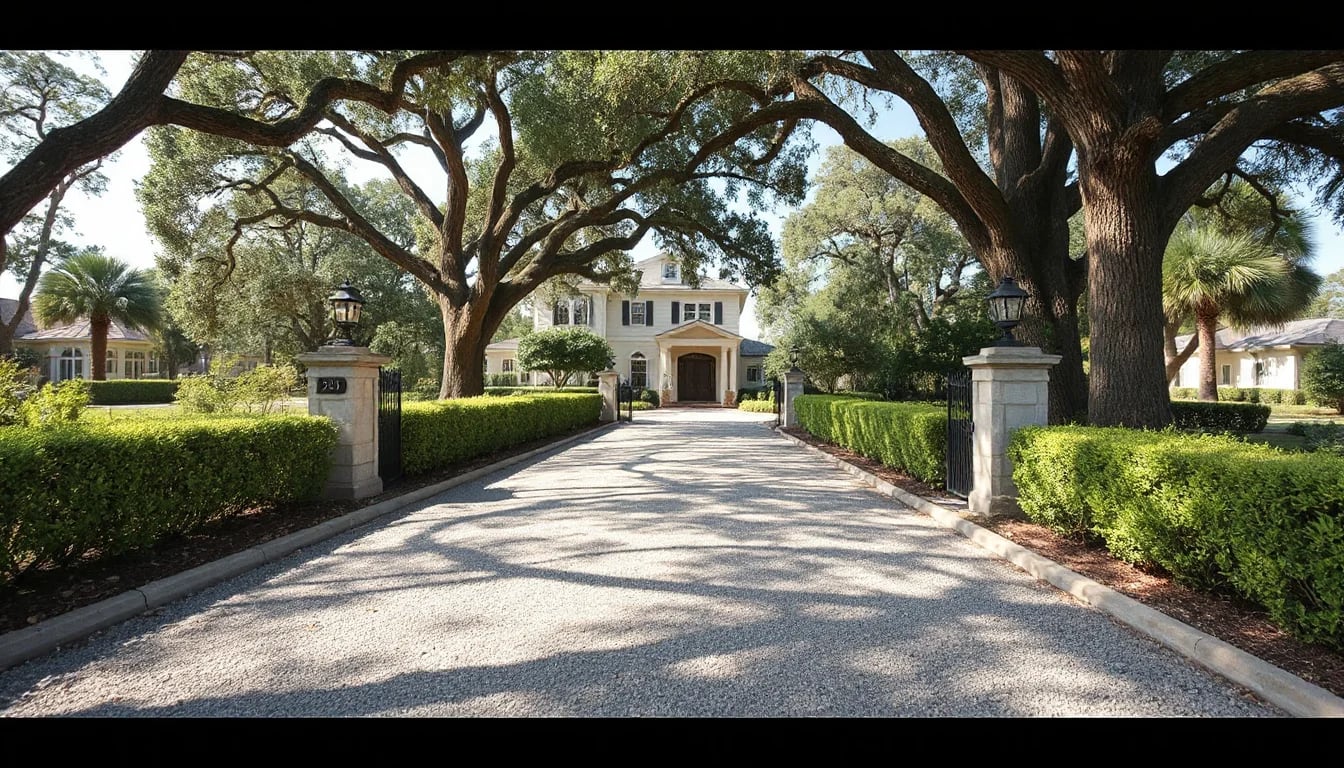
A first home purchase on Sullivan’s Island is about more than a list price. This barrier-island market has a limited supply of properties, distinctive architecture, beach access, and proximity to Charleston Harbor and the Atlantic. Buyers may encounter cottages, elevated coastal homes, renovated historic residences, and newer construction, each with its own maintenance profile and ownership costs. Before touring seriously, build a monthly budget that accounts for principal and interest, property taxes, homeowners insurance, possible flood insurance, wind coverage, utilities, maintenance, and any association fees that may apply.
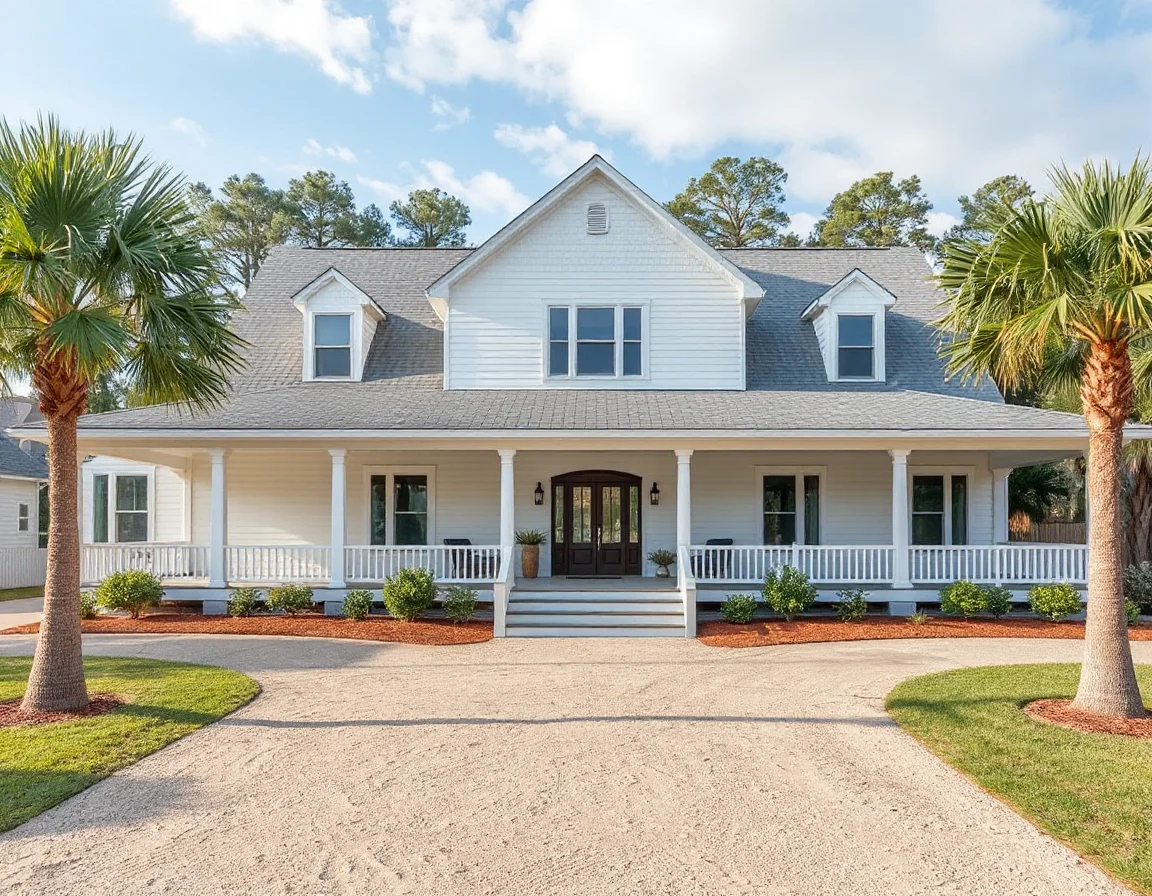
It is especially important to request realistic insurance quotes early. Coastal insurance availability, deductibles, wind provisions, and flood coverage can vary by property and insurer. A home’s age, roof condition, construction type, elevation, location within a flood zone, and proximity to water may influence premiums. Rather than waiting until a contract is underway, ask an insurance professional to provide preliminary estimates for homes that rise to the top of your list.
Cash reserves matter, too. In addition to the down payment and closing costs, set aside funds for inspections, appraisal-related expenses, insurance deposits, moving, repairs, and ongoing upkeep. On the coast, thoughtful ownership often includes routine attention to exterior paint, decks, railings, windows, roofing, drainage, HVAC systems, and salt-air exposure. A well-prepared budget gives you more confidence when the right opportunity appears.
A purchase price that works on paper can feel very different once insurance, deductibles, maintenance, and flood-zone considerations are added. Get property-specific estimates before making major decisions.
Prepare Your Financing Before You Fall for a Home
In a competitive market, a preapproval is more useful than a quick online estimate. Speak with a lender who understands the documentation and appraisal considerations that can come with coastal properties. They can review your income, assets, credit, debts, intended occupancy, and down-payment options, then explain a comfortable target range. Ask how the lender handles homes with elevated construction, substantial renovations, accessory spaces, or unusual property features that may affect underwriting or appraisal.
It helps to compare loan structures, not simply interest rates. Fixed-rate and adjustable-rate mortgages have different long-term tradeoffs, while the size of a down payment can affect monthly payments, mortgage insurance, reserve requirements, and offer strength. Buyers who are using funds from investments, gifts, business income, or another property sale should discuss documentation requirements well before writing an offer. Clear financial records can prevent avoidable delays once a contract is accepted.
A lender’s preapproval letter should be current, accurate, and aligned with the offer you intend to submit. Your real estate professional can help coordinate timing so your financing strategy supports the home search rather than slows it down. Keep major credit changes, new loans, unexplained deposits, and large purchases on hold until after closing unless your lender confirms otherwise.
Search Sullivan’s Island listings
Look Beyond the View: Property Due Diligence Matters
Coastal homes reward careful inspection. The goal is not to find a “perfect” property, but to understand its condition, systems, risks, and future maintenance needs. A comprehensive home inspection is a core part of that process. Depending on the home, buyers may also consider specialized evaluations for roofing, HVAC equipment, chimneys, docks, seawalls, pools, pest activity, drainage, foundation components, and structural elements.
Review available flood-zone information, elevation documentation, prior permits, survey materials, and seller disclosures. If a property has undergone additions or major improvements, ask what work was completed and whether permits and final approvals are available. For properties near marsh, beach, or waterways, clarify the condition and ownership details of any docks, bulkheads, access points, or other waterfront improvements. These features can be meaningful assets, but they also require informed review and continued care.
Historic character is another important part of Sullivan’s Island real estate. Older homes may offer architectural details that cannot be replicated, from porches and woodwork to traditional materials and proportions. At the same time, age can bring questions about electrical systems, plumbing, insulation, foundations, windows, and deferred maintenance. A knowledgeable inspection team and a measured review period can help buyers evaluate the home in context.
Do not overlook the day-to-day practicalities. Visit at different times when possible, test the route you expect to use most often, observe parking arrangements, and note sunlight, wind exposure, drainage patterns, and outdoor spaces. These details are not minor; they shape how a property functions over time.
Make an Offer With a Clear Strategy
Once you identify a home that fits your goals, an offer should reflect both the market and your personal comfort level. Price is only one term. Financing, due-diligence timing, requested seller contributions, closing date, included personal property, and contingency structure can all affect how an offer is received. The best strategy is not automatically the highest number or the shortest timeline. It is an offer that is financially sound, clearly written, and built around the information you need to proceed responsibly.
Review recent comparable sales, active competition, days on market, condition, lot characteristics, and meaningful upgrades with your agent. On an island where every property can be different, comparisons require nuance. A renovated home, a home with water views, an elevated structure, a larger lot, or a property with updated systems may not be directly comparable to another home just a few blocks away. Local context is essential when deciding where to begin and how much flexibility you have.
A strong first offer is one you can support through appraisal, inspections, insurance review, and closing—not simply one designed to win the first round of negotiations.
If your offer is accepted, stay organized through the contract period. Schedule inspections promptly, respond to lender requests quickly, track contingency deadlines, and keep all parties informed. A concierge-style approach can be particularly valuable in a detailed transaction, helping coordinate inspectors, lenders, insurance professionals, contractors, and closing tasks while you focus on decisions that matter most.
Explore Sullivan’s Island real estate
Plan for Ownership, Not Just Closing Day
Closing is an accomplishment, but it is also the start of stewardship. Create a property binder or digital folder with inspection reports, warranties, utility information, service contacts, insurance policies, surveys, permits, and maintenance records. Establish a seasonal maintenance schedule for exterior systems and arrange service for HVAC, roofing, pest prevention, and other components appropriate to the home. Consistent records can make future maintenance easier and can be useful if you eventually decide to sell.
Sullivan’s Island offers a distinct coastal environment shaped by beaches, maritime landscapes, historic sites, and the rhythms of the Lowcountry. Buying your first home here can be exciting, but the process works best when enthusiasm is paired with preparation. With a realistic budget, a well-matched lender, thorough inspections, thoughtful offer terms, and professional guidance, you can move from browsing listings to owning a home with clarity and confidence.